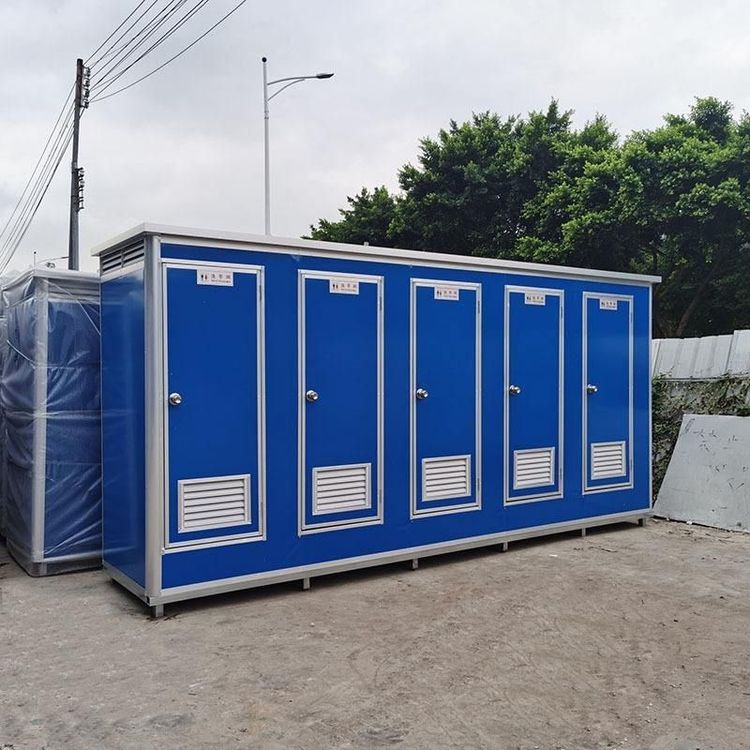
Accounting Entry for Purchasing Mobile Toilets
The accounting treatment for purchasing mobile toilets typically involves recording them as fixed assets and depreciating them under the category of tools and furniture. Detailed analysis is as follows:

I. Meeting the Definition of Fixed Assets
According to accounting standards, fixed assets must meet two core criteria: first, they must have a useful life exceeding one accounting year; second, they must be used for business management purposes. Although mobile toilets are movable, their intended use is for long-term service in business operations (such as construction sites, tourist attractions, etc.), and their useful life usually far exceeds one year, meeting the characteristic of “long-term use” for fixed assets. For example, if a company purchases mobile toilets for temporary rest for employees or visitor services, their usage cycle may span several years, making them typical operational assets.
II. Unit Value Exceeding the Threshold for Low-Value Consumables
Low-value consumables generally refer to items with a low unit value, that are easily worn out, and have a short usage cycle (such as office supplies, tools, etc.). If the cost of a single mobile toilet unit is 1,100 yuan and the total cost is 3,300 yuan, this exceeds the threshold for low-value consumables set by most companies (such as 500 yuan or 1,000 yuan). In this case, even though they are highly movable, they should be accounted for as fixed assets rather than being expensed as low-value consumables in a single摊销 (amortization) period.
III. Key Bases for Accounting Treatment
- Priority of Useful Life and Purpose: In accounting treatment, the value of an asset is not the sole criterion; the key determinants are its useful life and purpose. If mobile toilets are used for long-term business operations, they should be classified as fixed assets even if their unit price is relatively low.
- Depreciation Classification: Mobile toilets are usually depreciated under the category of “tools and furniture”. The depreciation period can refer to the minimum period specified by tax laws (such as 5 years), and the specific period should be determined based on the actual usage situation of the enterprise.
- Recording Process: Upon purchase, debit “Fixed Assets—Mobile Toilets” and credit “Bank Deposits” or “Accounts Payable”; subsequently, depreciate them periodically by debiting “Administrative Expenses” or “Manufacturing Expenses” and crediting “Accumulated Depreciation”.
IV. Special Circumstances
If mobile toilets are used temporarily (such as for exhibitions or events) or have an extremely low unit value (such as below 200 yuan), they can be treated as low-value consumables and expensed using the one-time摊销 (amortization) method. However, such cases should be evaluated comprehensively based on the company's accounting policies and actual usage.