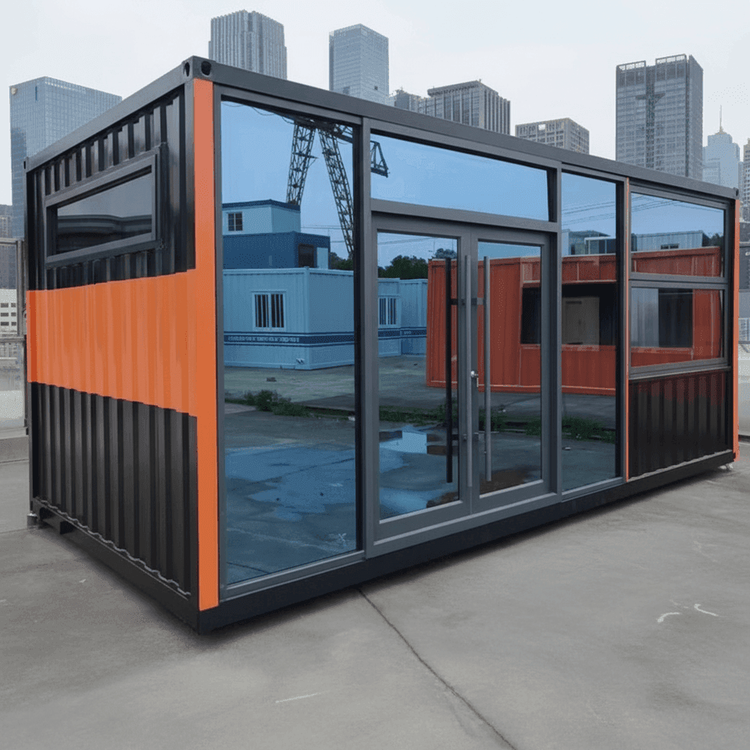
Is Container House Taxable Now?
Whether a container house is taxable needs to be judged based on specific circumstances. It mainly involves taxes such as value-added tax and property tax. Whether tax is payable depends on its use, whether it is recognized as real estate, and local tax regulations.

Value-Added Tax
If a container house is regarded as the leasing of tangible movable property, the general taxpayer's tax rate is 13%. For small-scale taxpayers, from January 1, 2023, to December 31, 2027, the levy rate is reduced to 1%. This is because the leasing of tangible movable property falls within the scope of value-added taxable items, and value-added tax is calculated and paid according to the corresponding tax rate or levy rate. If a container house is used for sales or import, the value-added tax rate may be 13% (the original 17% has been adjusted). The sales and import links also fall within the scope of value-added tax collection, and the corresponding tax rate is applied according to regulations.
Property Tax
According to the "Interim Regulations of the People's Republic of China on Property Tax", property tax takes buildings as the taxable object. If a container house is recognized as real estate in the traditional sense, for example, if it is fixed at a certain location and used for production and business operations, the property owner needs to pay property tax based on the original value of the property or rental income. This is because it has the characteristics of the fixity of real estate and being used for production and business operations, meeting the taxable conditions for property tax. However, if it is only used as a temporary and movable container, it is generally not regarded as real estate and no property tax is required. Nevertheless, whether it is specifically recognized as real estate is subject to the interpretation of the local tax department, and there may be differences in the recognition of container houses in different regions.
Other Taxes
- Additional Taxes and Fees: Calculated based on the amount of value-added tax, including urban maintenance and construction tax (with tax rates of 7%, 5%, or 1%), education surcharge (3%), and local education surcharge (2%). These additional taxes and fees are calculated and paid according to the corresponding proportions on the basis of paying value-added tax.
- Stamp Duty: Property leasing contracts are levied at a rate of one-thousandth of the leasing amount, and may be eligible for a 50% reduction or exemption. If a container house involves leasing business and a property leasing contract is signed, stamp duty needs to be paid according to regulations.
- Deed Tax: Generally, no deed tax is required to be paid since the property rights of container houses usually do not transfer. Deed tax is mainly levied when property rights are transferred, and since container houses generally do not involve property rights transfer, no deed tax is usually required.
Since the tax situation of container houses is relatively complex, it is advisable to consult the tax department or a professional lawyer to obtain accurate information.
You may also like
Container House Installation Guide: A Complete Walkthrough
Read More
Portable Toilet Eco-Friendly Custom & OEM: Design & Bulk Production Guide
Read More
How to Assemble & Install Container House Step by Step
Read More