Portable Toilet Competitive Analysis
The competitive analysis of portable toilets should start from market segments and product types, covering four major areas: portable commodes, ecological toilets, smart public toilet systems, and mobile restroom models. The core competitive dimensions include price, technology, and scenario adaptability.

I. Portable Commode Market: Coexistence of Basic Models and High-End Penetration
The domestic market is dominated by simple models (PE plastic one-piece molding, weighing 1.5-3kg, relying on disposable waste bags), with competition focusing on cost control and channel coverage, suitable for scenarios such as elderly care and outdoor camping. Packaged models and self-contained freshwater and wastewater models form a price gradient, covering needs in engineering infrastructure and emergency disaster relief. High-end niche categories such as vehicle-mounted pull-out models, healthcare barrier-free models, and biodegradable eco-friendly models compete for niche markets through functional differentiation (e.g., sealing performance, smart maintenance). Overseas high-end categories (e.g., biodegradable eco-friendly models) leverage technological barriers (eco-friendly materials, smart maintenance) to enter the domestic high-end market, forming differentiated competition with local brands.
II. Ecological Toilet Market: Driven by Scale Expansion and Technological Iteration
The competitive landscape is composed of upstream raw material suppliers, midstream production and processing links, and downstream application areas (cultural tourism attractions, municipal projects). Leading enterprises reduce costs through full industry chain integration (e.g., self-supply of raw materials, production automation), while small and medium-sized manufacturers focus on regional markets or customized needs. Production capacity is driven by the explosive growth of downstream cultural tourism activities and the upgrading of municipal environmental protection standards, requiring enterprises to upgrade product technologies (e.g., wastewater purification, energy-saving design) to meet demand.
III. Smart Public Toilet System: Full-stack Self-Research Capability as a Core Barrier
First-tier manufacturers (e.g., Guangzhou Zhongqi Technology) possess core software and hardware self-research capabilities, full-scenario solution implementation experience, and a comprehensive service system, leading technological iteration and product upgrades, and becoming the preferred choice for government and enterprise projects. Small and medium-sized manufacturers in the second and third tiers are gradually eliminated due to a lack of full-stack capabilities, while workshop-style enterprises focus on the low-end market but face policy compliance risks (e.g., data security, environmental protection standards).
IV. Mobile Restroom Models: Material and Scenario Adaptability as the Core
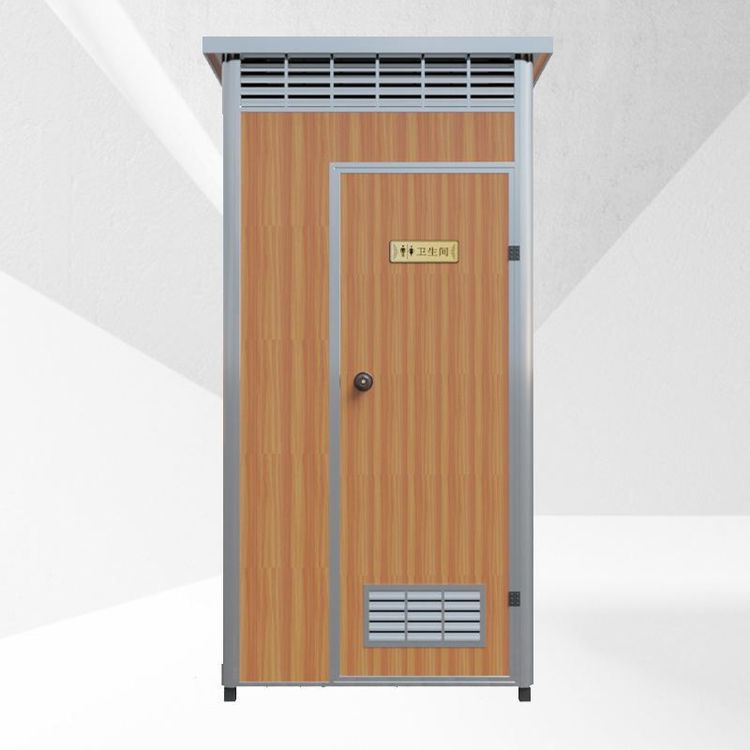
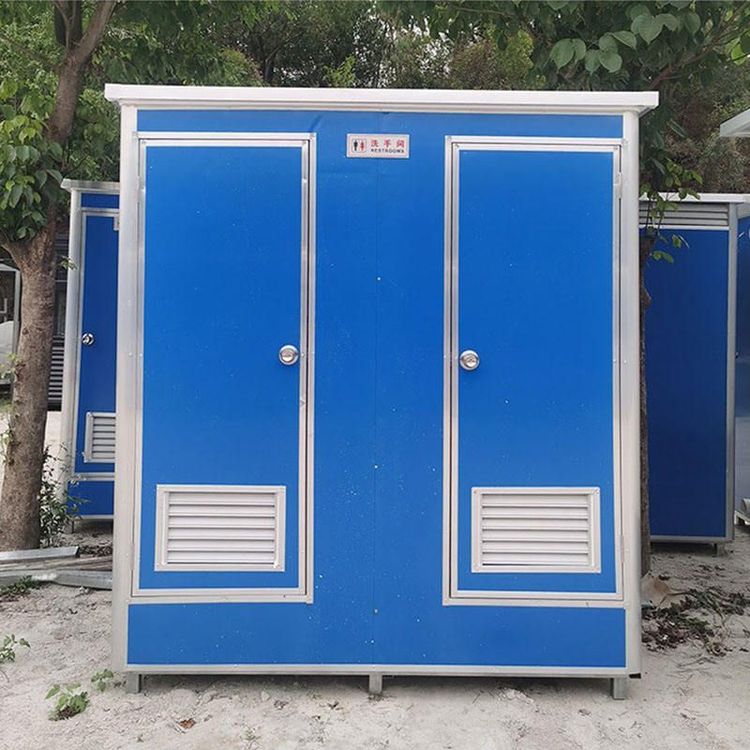
Color-steel sandwich panels are cost-effective and quick to deliver, suitable for construction sites; stainless steel is corrosion-resistant and easy to clean, suitable for transportation hubs; metal carved and faux wood models meet the needs of scenic spots and municipal projects through customized appearances. Key selection indicators include scenario adaptability (durability, odor control), budget level (cost differences between basic and customized models), and usage cycle (choice between leasing and purchasing models).