Value-Added Tax on Mobile Toilets
The value-added tax (VAT) situation for mobile toilets needs to be differentiated based on specific business scenarios, mainly including three cases: corporate purchases, operational leases, and invoicing for leases in Hunan Province. Details are as follows:

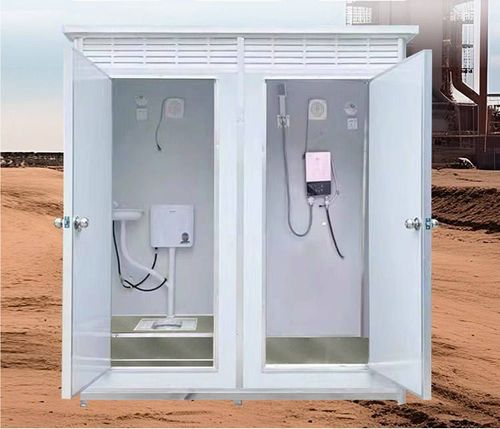
I. VAT Treatment for Corporate Purchases of Mobile Toilets The VAT deduction for corporate purchases of mobile toilets must meet three conditions: purpose, documentation, and project nature. If the mobile toilet is used for production and business activities (such as temporary facilities on construction sites) and a valid VAT special invoice is obtained, its input tax can be deducted from the output tax. If it is used for non-VAT taxable projects (such as collective welfare facilities like employee dormitories), even with a special invoice, the input tax cannot be deducted. Additionally, if a valid deduction document (such as an ordinary invoice or no invoice) is not obtained, the input tax cannot be deducted even if the purpose complies with regulations. For example, if a construction company purchases a mobile toilet for use by workers on a construction site and obtains a special invoice, it can be deducted normally; if used for employee dormitories, the input tax must be transferred out.
II. VAT Rate for Operational Leases of Mobile Toilets Operational leases of mobile toilets generally fall under the category of providing tangible movable property leasing services, with a VAT rate of 13% (for general taxpayers). If the lessor is a small-scale taxpayer, a 5% levy rate applies (subject to adjustment during tax incentive periods). For example, if a leasing company leases mobile toilets as a general taxpayer, it must issue a special invoice at a 13% rate; if it is a small-scale taxpayer, it issues an invoice at a 5% levy rate, and the purchaser, if a general taxpayer, can calculate and deduct input tax at 3% (under current policies, small-scale taxpayers issuing special invoices can deduct at 1% or 3%).
III. Invoicing Rules for Mobile Toilet Leases in Hunan Province In Hunan Province, the invoicing method for mobile toilet leases must distinguish between billing cycles and invoice types: when billed by the day or hour, a VAT ordinary invoice is issued by default, with the cost including taxes; if a VAT special invoice is required, an additional 6% tax may be charged (subject to the actual tax rate). For example, if a company leases a mobile toilet on a daily basis and the lessor issues an ordinary invoice, there is no need to separately list the tax; if a special invoice is requested, a 6% tax must be paid additionally (the actual tax rate may change due to policy adjustments and must comply with local tax authority regulations).
Summary: The VAT treatment for mobile toilets must be comprehensively judged based on business nature, taxpayer status, and regional policies. For corporate purchases, strict differentiation between purpose and documentation is required; for operational leases, the applicable tax rate must be clarified based on the taxpayer's status; for leases in Hunan Province, attention must be paid to the differences in invoice types and taxes. It is recommended to consult local tax authorities or professional institutions during actual operations to ensure compliance.