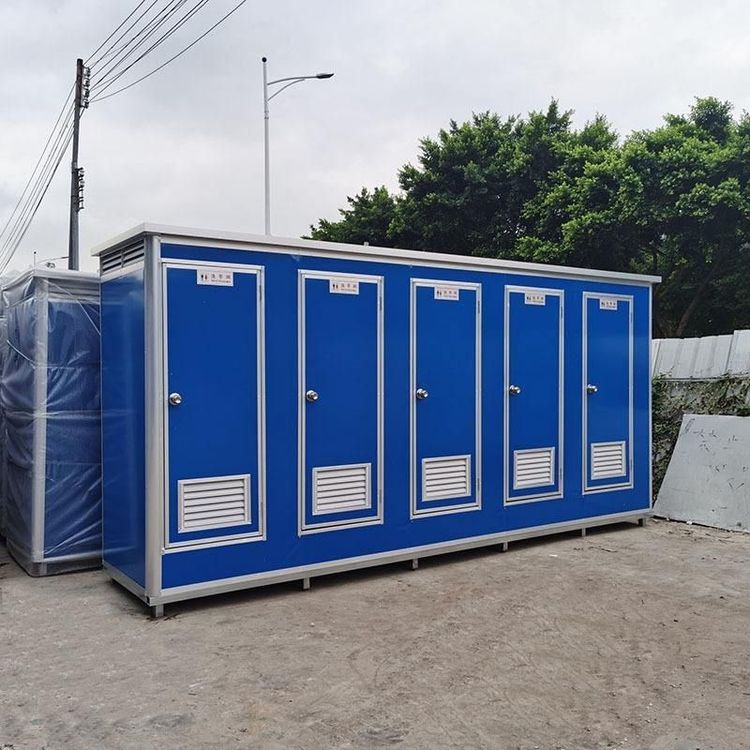
Mobile Toilet Tax Point
The tax point for mobile toilets varies depending on the taxpayer's identity. The tax rate for general taxpayers is 13%, while the levy rate for small-scale taxpayers is 3%. Here is a detailed introduction:

Tax Classification Code and Name
The tax classification code for mobile toilets is 1080409, and the tax classification name is containers. Although the actual product is a mobile toilet, it is classified as a container in the tax classification system. This may be because mobile toilets share certain similarities with containers in terms of structure and functionality, such as having a certain degree of enclosure and mobility. Therefore, they are classified as containers for tax administration purposes in accordance with relevant regulations.
Invoice Item Name
The invoice item name is Metal Products Mobile Toilet. This indicates that when issuing an invoice, it is necessary to clearly label the product as a mobile toilet in the metal products category. This naming method helps accurately define the nature and purpose of the product, facilitating tax administration by tax authorities and financial accounting by enterprises. At the same time, for buyers, it enables them to clearly understand the specific information of the purchased product, ensuring the transparency and legality of the transaction.
Tax Points for Different Taxpayer Identities
- General Taxpayers: The applicable tax rate for general taxpayers selling mobile toilets is 13%. General taxpayers usually have relatively large business scales and well-established financial accounting systems, enabling them to accurately deduct input tax and calculate output tax in accordance with value-added tax regulations. The 13% tax rate is one of the common tax rates applicable to general taxpayers for selling goods, providing processing, repair, and replacement services, and other typical business activities. As mobile toilets are sold as goods, this tax rate applies.
- Small-Scale Taxpayers: The levy rate for small-scale taxpayers selling mobile toilets is 3%. Small-scale taxpayers generally have relatively small business scales and less well-established financial accounting systems. To simplify tax administration and reduce the tax burden and compliance costs of small-scale taxpayers, the state adopts a simplified tax calculation method for them, calculating the tax payable based on sales revenue and the levy rate without deducting input tax. Therefore, small-scale taxpayers pay value-added tax at a levy rate of 3% when selling mobile toilets.