Asset Category of Mobile Toilets
The asset category of mobile toilets falls under buildings and structures. The following analysis is conducted from three perspectives: definition, accounting standards, and tax regulations.

Core Characteristics Aligning with Fixed Asset Definition
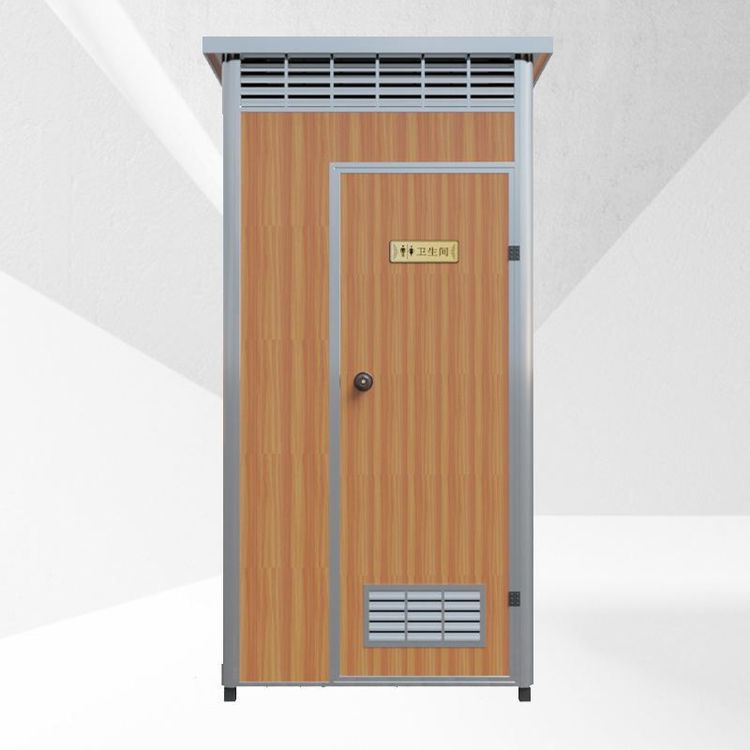
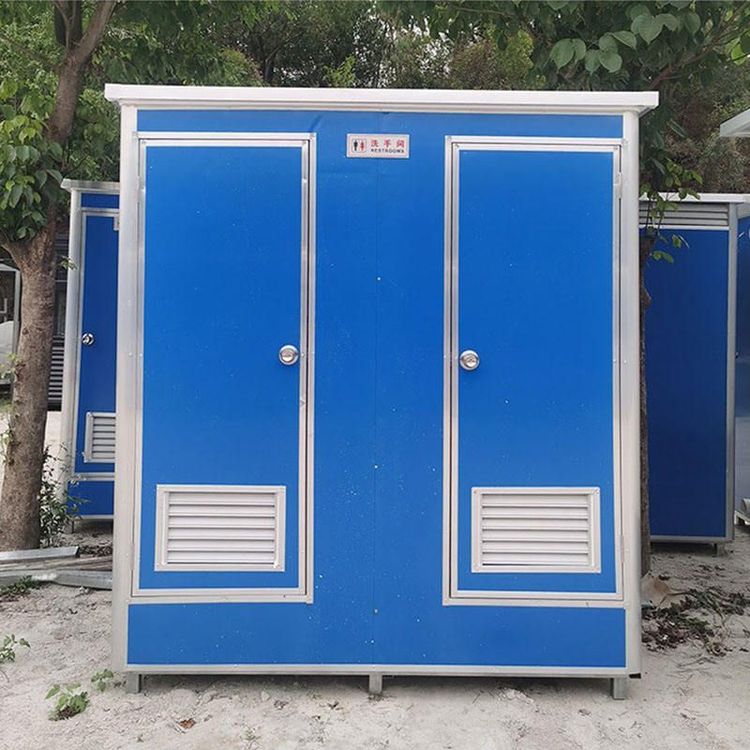
Although mobile toilets possess mobility, their essence remains long-term assets held by enterprises for business management purposes. According to accounting standards, fixed assets must meet two core conditions: first, they are held for producing goods, providing services, renting, or business management; second, their useful life exceeds one accounting year (typically 12 months). Mobile toilets are usually purchased by enterprises and deployed long-term at specific locations (such as scenic spots, construction sites, and temporary event venues) to meet the toilet needs of the public or employees, serving as essential facilities for business management activities. Their useful life generally exceeds 12 months, and costs are allocated through depreciation, aligning with the 'long-term use' attribute of fixed assets.
Classification Basis in Accounting Standards
According to 'Accounting Standards for Business Enterprises No. 4 - Fixed Assets', the classification of fixed assets should consider both their physical form and functional use. Although mobile toilets are movable, their structure includes complete architectural elements such as walls, roofs, and sanitary facilities, and their function is essentially the same as that of fixed public toilets, both providing sheltered spaces and sanitary services. Furthermore, both International Financial Reporting Standards (IFRS) and Chinese accounting standards emphasize the 'substance over form' principle, meaning asset classification should be based on economic substance rather than physical form. The economic substance of mobile toilets is that of long-term operational facilities, not liquid assets that can be disposed of at any time, and thus they should be classified as buildings and structures.
Explicit Provisions in Tax Regulations
Article 57 of the 'Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China' explicitly lists 'buildings and structures' as an independent category of fixed assets and defines them as 'buildings and structures and their附属设施 (ancillary facilities) used for production, business operations, and employee welfare services'. As facilities purchased by enterprises for business operations or employee welfare, mobile toilets highly align with the scope of 'ancillary facilities' in tax regulations. In tax practice, expenditures by enterprises on purchasing mobile toilets are usually depreciated and deducted as assets in the category of buildings and structures, further confirming their classification.
In conclusion, mobile toilets should be classified as buildings and structures due to meeting the definition of fixed assets, aligning with classification standards in accounting standards, and being explicitly stipulated in tax regulations.