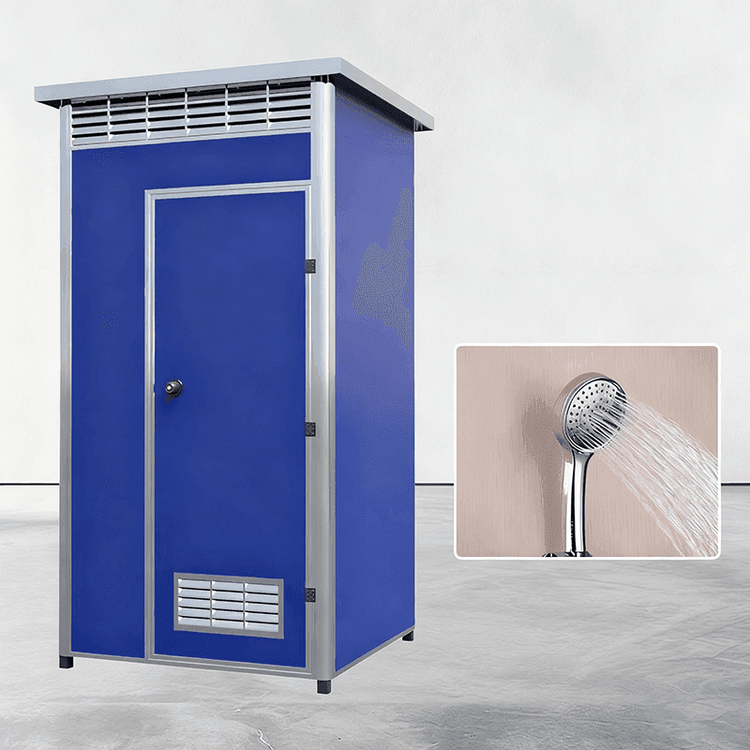
Accounting Treatment for Mobile Toilets
The accounting classification of mobile toilets should be determined based on a comprehensive assessment of their value, purpose, and service life. Common treatment methods are as follows:

I. Accounting as Fixed Assets (Key Criteria: High Value, Long-Term Use, Operational Purpose)
If the unit price of a mobile toilet exceeds the enterprise's fixed asset recognition threshold (e.g., a common threshold of 12,000 yuan), has a service life exceeding one year, and is directly used for production and business activities (e.g., in tourist attractions or construction sites), it should be recorded under the 'Fixed Assets—Mobile Toilets' account.
Specific Process:
- Procurement Stage: When making payment, debit 'Fixed Assets—Mobile Toilets' and credit 'Bank Deposit' or 'Cash'.
- Installation and Commissioning: If installation costs are involved, first accumulate costs under 'Construction in Progress—Mobile Toilets'. After installation is completed and accepted, transfer to the 'Fixed Assets' account.
- Subsequent Depreciation: Depreciate over the estimated service life, debiting 'Administrative Expenses—Depreciation Expense' (for administrative purposes) or 'Selling Expenses—Depreciation Expense' (for operational purposes), and crediting 'Accumulated Depreciation'.
Basis: According to the 'Accounting Standards for Business Enterprises No. 4—Fixed Assets', assets meeting fixed asset criteria must be treated in this manner to align with their long-term use attributes.
II. Accounting as Expenses or Welfare Expenses (Applicable Conditions: Low Value or Employee Welfare Purpose)
If the mobile toilet has a low value (below the fixed asset threshold) or is primarily used for employee welfare (e.g., for workshop employees), it can be recorded under current profit and loss accounts:
- Direct Expensing: Debit 'Administrative Expenses—Maintenance Expenses' or 'Selling Expenses—Other Expenses', and credit 'Bank Deposit'.
- Welfare Expense Treatment: If explicitly for employee welfare, first transition through 'Employee Benefits Payable—Welfare Expenses', then transfer to relevant expense accounts.
Note: If the asset has a low value but a service life exceeding one year, it should still be accounted for as a fixed asset to avoid underestimating asset scale.
III. Special Scenario Treatment
- Rental Income: If the enterprise rents out mobile toilets, rental income is recorded under 'Operating Revenue—Rental Income', with corresponding recognition of VAT output tax.
- Tax Treatment: VAT paid during procurement (if deductible) is recorded under 'Taxes Payable—VAT Payable (Input Tax)'; when renting out, output tax must be accrued, debiting 'Bank Deposit' and crediting 'Operating Revenue—Rental Income' and 'Taxes Payable—VAT Payable (Output Tax)'.
Practical Recommendations
- Prioritize Fixed Asset Assessment: Evaluate based on service life, value, and purpose to avoid misclassification.
- Improve Voucher Management: Procurement contracts, invoices, installation acceptance documents, etc., should be attached as original vouchers to accounting vouchers to ensure compliance.
- Dynamically Adjust Accounts: If asset purpose changes (e.g., from operational to employee welfare), promptly adjust account classification and adjust depreciation accordingly.