What Accounting Subject Should Mobile Toilets Be Classified Under
Mobile toilets should generally be classified under the fixed assets account.
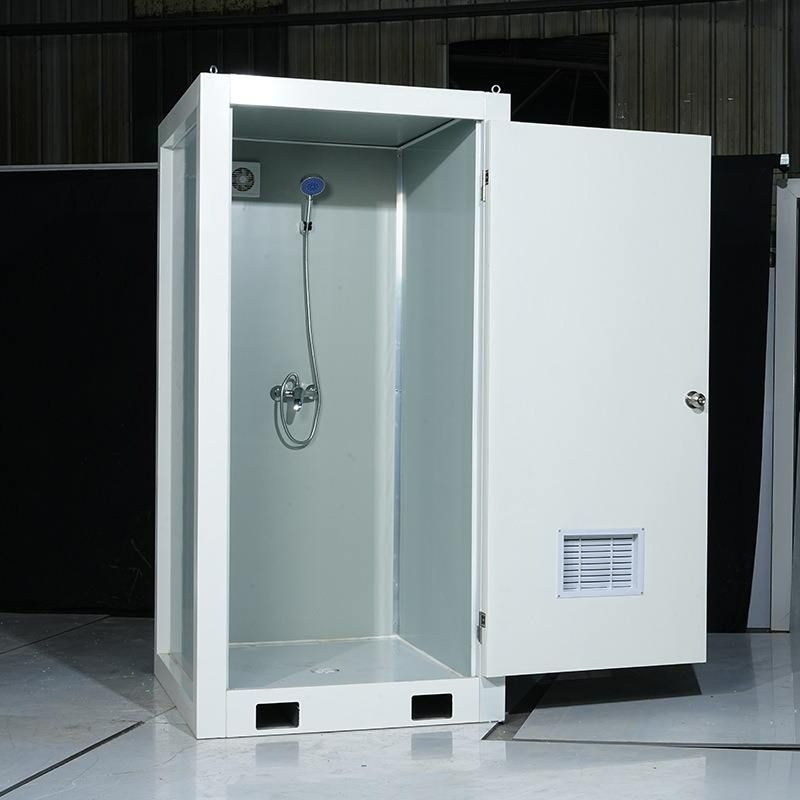
From the perspective of accounting standards, fixed assets refer to tangible assets held by an enterprise for the production of goods, provision of services, leasing, or business management, with a useful life exceeding one accounting year. Although mobile toilets have the characteristic of mobility, their useful life typically exceeds one accounting year. Moreover, enterprises usually purchase mobile toilets for business management needs, such as setting them up at large event venues, construction sites, tourist attractions, and other locations to facilitate personnel use and meet the operational requirements of the enterprise. Therefore, they meet the accounting criteria for fixed assets.
In terms of specific accounting treatment, when an enterprise purchases a mobile toilet, it needs to make corresponding accounting entries. At this time, it should debit the 'Fixed Assets - Mobile Toilet' account and credit accounts such as 'Bank Deposit' or 'Accounts Payable'. This indicates an increase in the enterprise's assets (fixed assets) and a change in the source of funds (a decrease in bank deposits or an increase in accounts payable). Subsequently, when depreciation is accrued according to the enterprise's established depreciation policy, it should debit the 'Depreciation Expense' account and credit the 'Accumulated Depreciation' account. Through such accounting treatment, the value changes of mobile toilets in the enterprise's assets and the cost allocation during their use can be accurately reflected.
In addition, as fixed assets, the classification of mobile toilets in an enterprise's accounting books may vary depending on the enterprise. For example, in some industrial enterprises, they may be classified as 'Machinery and Equipment'; for construction enterprises, they may be categorized as 'Structures'; for sanitation service enterprises, they may be included in categories such as 'Special Equipment' or 'Sanitation Equipment'; and at tourist attractions and other venues, they may be regarded as 'Mobile Service Facilities' or 'Public Infrastructure'. The specific classification mainly depends on the industry nature of the enterprise and its internal management needs.
You may also like
Portable Toilet Used in 2026: Buying Guide & Recommendations
Read More
Portable Toilet Custom Explained: How to Choose the Right One
Read More
Top Portable Toilet Smart Manufacturers: How to Choose a Factory Partner
Read More