Which Accounting Category Does Mobile Toilet Belong To
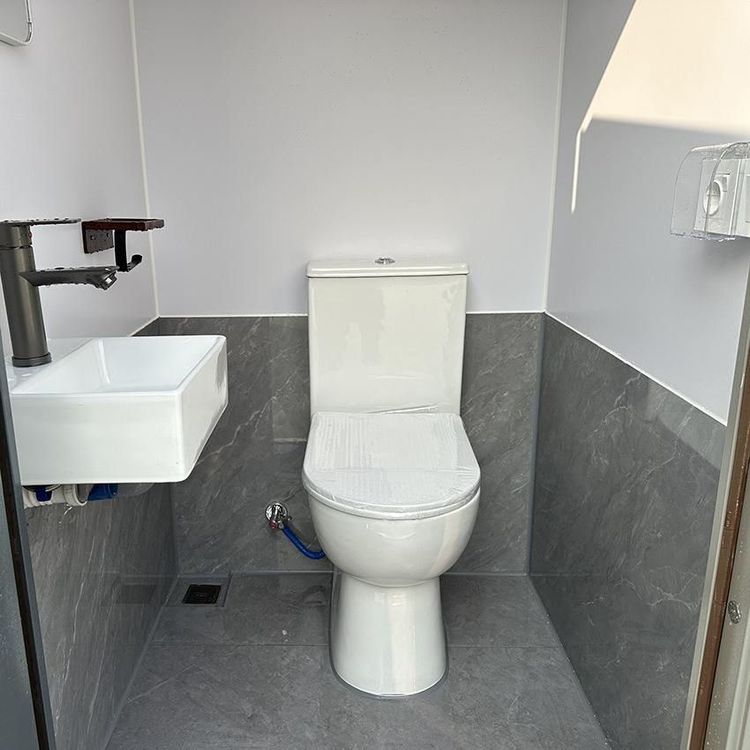
Mobile toilets are typically classified as fixed assets.

Basis for Fixed Asset Identification
According to Article 57 of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China and the relevant provisions of Accounting Standards for Business Enterprises No. 4 - Fixed Assets (2006 Edition), fixed assets must meet two core conditions: first, they are held by an enterprise for business management purposes; second, their usage period exceeds 12 months. If a mobile toilet meets these conditions, it is identified as a fixed asset. For example, mobile toilets purchased by enterprises for scenic spots, construction sites, or temporary event venues are included in the scope of fixed asset accounting because they serve business management activities for a long time and usually have a usage cycle of more than one year.
Classification Differences in Accounting Treatment
In accounting practice, the specific classification of mobile toilets may vary due to industry characteristics or functional differences. For example:
- Mechanical Equipment Category: If a mobile toilet has mechanical structures (such as automatic flushing and sewage discharge systems), it may be classified as 'mechanical equipment';
- Structures Category: If a mobile toilet has a fixed structure (such as a concrete base), it may be classified as a 'structure';
- Special Equipment Category: If a mobile toilet involves pressure vessels or special safety standards (such as high-temperature disinfection equipment), it may be classified as 'special equipment';
- Other Functional Categories: Depending on the usage scenario, it may also be classified as 'mobile service facilities', 'public infrastructure', 'sanitation equipment', 'green assets', 'tourism supporting facilities', or 'temporary facilities', etc.
Accounting Treatment for Procurement and Low-Value Assets
- Fixed Asset Procurement: When an enterprise purchases a mobile toilet, it usually debits the 'Fixed Assets - Mobile Toilet' account and credits the 'Bank Deposit' or 'Cash' account, reflecting the corresponding relationship between asset increase and fund decrease.
- Low-Value Asset Treatment: If the value of a mobile toilet is relatively low (e.g., around 2000 yuan), according to the principle of materiality, it can be directly recorded in the 'Administrative Expenses - Other Expenses' account to avoid increasing management costs due to overly detailed accounting of small-value assets.
Flexibility of Classification Basis
The accounting classification of mobile toilets is not absolute and needs to be comprehensively judged based on their design structure, usage scenario, and industry practices. For example, mobile toilets in scenic spots may focus more on the 'tourism supporting facilities' classification, while those in construction sites may focus more on the 'temporary facilities' classification. Enterprises should choose the most appropriate classification method according to their actual needs to ensure that accounting information truly reflects the attributes and uses of assets.