Back to blog
Article
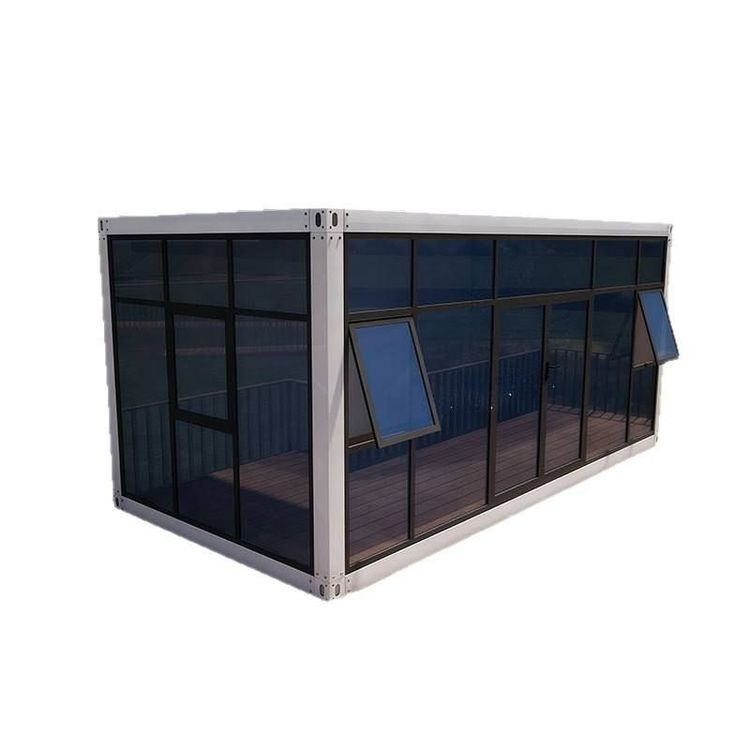
Tax on Leasing Activity Houses and Containers
Admin September 17, 2026
The determination of the tax on leasing activity houses and containers requires a comprehensive assessment based on the type of taxpayer, tax calculation method, and property attributes, as detailed below:

I. Real Estate Leasing Scenarios (if classified as real estate)
General Taxpayers
- General Tax Calculation Method: Applicable to real estate acquired after May 1, 2016, with a tax rate of 9%. The formula for calculating tax payable is: Tax Payable = Current Output Tax - Current Input Tax, where Output Tax = Tax-inclusive Sales Amount ÷ (1 + 9%) × 9%.
- Simplified Tax Calculation Method: Applicable to real estate acquired before April 30, 2016, with a collection rate of 5%. The formula for calculating tax payable is: Tax Payable = Tax-inclusive Sales Amount ÷ (1 + 5%) × 5%.
Small-scale Taxpayers
- The collection rate for leasing non-residential properties is 5%; for leasing residential properties, it is 5% but reduced to 1.5% for calculation.
- From January 1, 2023, to December 31, 2027, they are eligible for a 50% reduction in the "Six Taxes and Two Fees" (including property tax).
Other Individuals (Natural Persons)
- The collection rate for leasing non-residential properties is 5%; for leasing residential properties, it is 5% but reduced to 1.5% for calculation, and they must file tax returns with the competent tax authority where the real estate is located.
II. Movable Property Leasing Scenarios (if classified as movable property)
General Taxpayers
- General Tax Calculation Method: The tax rate for providing tangible movable property leasing services (including container mobile home leasing) is 13%.
- Simplified Tax Calculation Method: If choosing "tangible movable property operating leasing services" under operating leasing services, the collection rate is reduced to 3%.
Small-scale Taxpayers
- They usually calculate tax payable at a collection rate of 3%, but from January 1, 2023, to December 31, 2027, taxable sales income subject to a 3% collection rate is reduced to a 1% collection rate for VAT purposes.
Other Individuals (Natural Persons)
- The collection rate for leasing tangible movable property is 3%, reduced to a 1% collection rate from January 1, 2023, to December 31, 2027.
III. Special Policies (Housing Rental Enterprises)
If an enterprise leases residential properties (including affordable rental housing) to individuals, general taxpayers can choose the simplified tax calculation method at a 1.5% collection rate or apply the general tax calculation method; small-scale taxpayers calculate tax at a 1.5% collection rate.
Notes:
- There is no unified regulation on tax codes, and reference should be made to the opinions of local tax authorities or professionals.
- In practice, it is recommended to make a comprehensive assessment based on the taxpayer's identity, real estate/movable property attributes, and policy timeliness, and consult the tax authority for confirmation.