Accounting Subject for Mobile Toilets
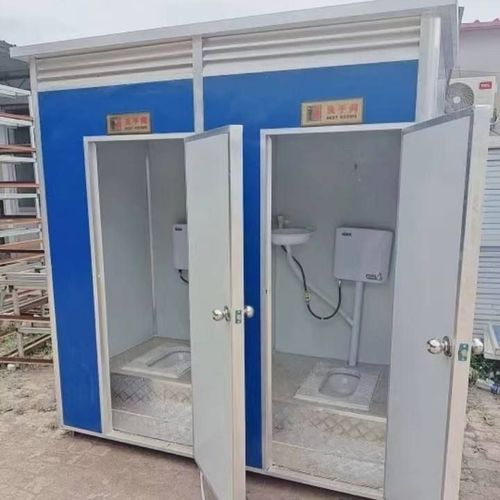
Mobile toilets are typically classified under the 'Fixed Assets' category. According to accounting standards, fixed assets must meet three criteria simultaneously: a useful life exceeding one year, relatively high unit value (usually reaching the capitalization threshold set by the enterprise), and being held for production and business activities. Despite their mobility, mobile toilets are designed to last beyond one accounting year and serve as essential infrastructure in enterprise management (such as in tourist attractions, construction sites, temporary event venues, etc.), meeting the accounting standards for fixed assets.

Core Basis for Accounting Treatment
Useful Life and Value Criteria
The materials (such as metal frames, eco-friendly materials) and structure of mobile toilets determine their useful life typically ranges from 5 to 10 years, far exceeding the one-year accounting period requirement. If the procurement cost reaches the enterprise's fixed asset capitalization threshold (e.g., exceeding 5,000 yuan for a single purchase, with specific standards varying by enterprise policy), it should be recorded as a fixed asset rather than expensed.Functional Attributes and Holding Purpose
Enterprises purchase mobile toilets to provide long-term sanitation support, serving as ancillary facilities for production and business activities rather than short-term consumables. For example, mobile toilets installed at construction sites to meet workers' needs or temporary sanitation facilities provided at tourist attractions for visitors both meet the criteria of being 'held for production and business purposes'.
Depreciation Classification and Account Setup
Depreciation treatment for mobile toilets is usually categorized under 'Tools and Furniture' or similar accounts, with specific account names adjusted based on the enterprise's industry attributes:
- Manufacturing/Construction Industry: May be classified as 'Machinery and Equipment' or 'Mobile Service Facilities', emphasizing their mobility and service functions;
- Service/Tourism Industry: May be categorized as 'Structures' or 'Special Equipment', highlighting their infrastructure attributes;
- General Classification: Some enterprises directly use the 'Fixed Assets - Other' account and specify the purpose in remarks.
Compliance Requirements
Enterprises must comply with the 'Accounting Standards for Business Enterprises No. 4 - Fixed Assets' and relevant tax laws to ensure proper accounting treatment:
- Capitalization and Expensing Boundaries: If the procurement cost of mobile toilets is relatively low (e.g., in leasing form or simple models), they can be recorded as 'Low-Value Consumables' or directly expensed;
- Depreciation Method Selection: The straight-line method is typically used for depreciation, with the residual value rate determined based on actual usage (e.g., 5%-10%);
- Tax Treatment: Depreciation expenses can be deducted before corporate income tax, but procurement contracts, invoices, and other supporting documents must be retained for tax verification.
Enterprises should reasonably set up accounting accounts and standardize processing procedures based on their industry characteristics, management needs, and tax compliance requirements.