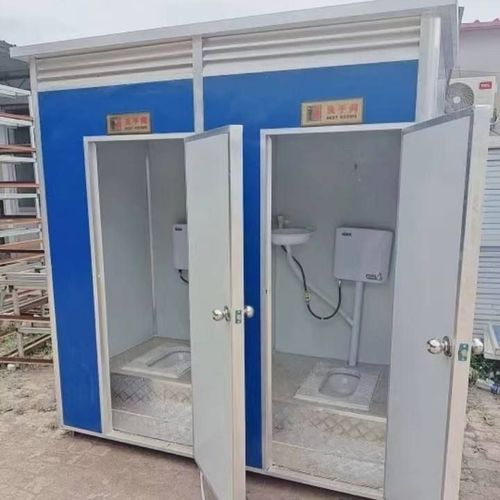
Accounting Category for Mobile Toilets
Mobile toilets are generally recorded under the 'Fixed Assets' category, and in special cases, they can be recorded under 'Administrative Expenses - Other Expenses'. Here is a detailed analysis:

Recording as Fixed Assets When Conditions Are Met
According to accounting standards, if a mobile toilet meets conditions such as a useful life exceeding one year, a relatively high unit value, and being held for production and business activities, it should be recorded under the 'Fixed Assets' category. For example, a mobile toilet purchased by a company for 12,000 yuan, due to its high value and long-term service to production and business operations, needs to be accounted for as a fixed asset. The company needs to confirm the original asset value at the time of purchase and subsequently depreciate it over the estimated useful life, allocating the depreciation expense to relevant cost or expense categories based on the asset's use.
Recording as Administrative Expenses When Value Is Low
If the unit value of a mobile toilet is relatively low (e.g., around 2,000 yuan) and does not meet the criteria for fixed asset recognition, it can be directly recorded under 'Administrative Expenses - Other Expenses' in the current period's profit and loss. However, it should be noted that if a company simultaneously purchases multiple low-value assets (e.g., air conditioners, refrigerators) with a significant total amount, even if the individual values are low, it is still recommended to combine and record them under the 'Fixed Assets' category to more accurately reflect asset scale and depreciation.
Determining Fixed Asset Classification Based on Usage
In the classification of fixed assets, the归属 (category) of mobile toilets needs to be comprehensively judged based on the company's industry attributes and asset functions. For example, if used in a production workshop, they may be classified under the 'Machinery and Equipment' sub-category; if dedicated to sanitation services, they may be classified under the 'Sanitation Equipment' sub-category; if used in mobile service scenarios (e.g., exhibitions, construction sites), they may be classified under the 'Mobile Service Facilities' sub-category. The classification basis should focus on the actual use of the asset to ensure that accounting treatment aligns with the business essence.
Recommendations for Special Cases
For mobile toilets at the value threshold (e.g., 5,000 yuan), companies can make a comprehensive judgment based on internal asset management systems and tax requirements. If simplified treatment (e.g., direct expensing) is adopted, it must comply with tax law definitions of low-value consumables; if recorded as fixed assets, depreciation policies and subsequent management processes must be standardized to avoid tax risks.