What Accounting Category Does a Mobile Toilet Belong To?
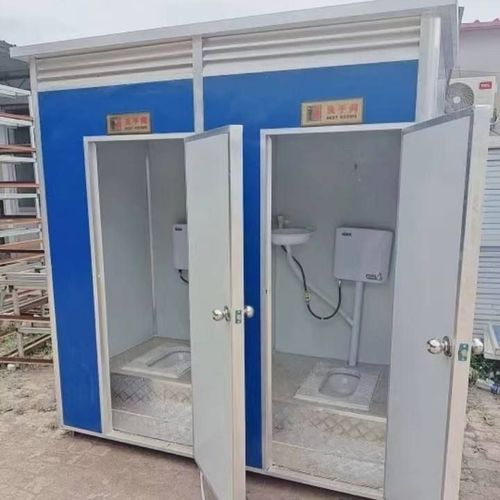
Mobile toilets should generally be classified under the fixed assets category.

From the perspective of accounting standards, fixed assets refer to tangible assets held by an enterprise for the production of goods, provision of services, leasing, or administrative management, with a useful life exceeding one accounting year. Although mobile toilets possess the characteristic of mobility, their useful life typically exceeds one accounting year and they serve the administrative management needs of the enterprise, thus fully meeting the accounting criteria for fixed assets. For example, if an enterprise purchases a mobile toilet worth 12,000 yuan, it should be recorded under the fixed assets category in accordance with accounting standards.
In terms of accounting treatment, mobile toilets, as fixed assets, involve multiple accounting categories:
- At the time of purchase: When an enterprise purchases a mobile toilet, the accounting entry should debit the 'Fixed Assets - Mobile Restroom' category and credit categories such as 'Bank Deposits' or 'Accounts Payable'. This reflects the increase in enterprise assets and the corresponding changes in funds or liabilities.
- During depreciation: Based on the enterprise's established depreciation policy, depreciation is accrued for the mobile toilet. The accounting entry at this time is to debit the 'Depreciation Expense' category and credit the 'Accumulated Depreciation' category. Through this method, the value of the mobile toilet is gradually allocated to various accounting periods during its use, providing a more accurate reflection of the enterprise's costs and profits.
- When maintenance and repair expenses occur: When the mobile toilet requires maintenance or repair, corresponding expenses are incurred. In accounting treatment, the 'Maintenance Expense' category is debited, and categories such as 'Bank Deposits' or 'Raw Materials' are credited. This records the expenses incurred by the enterprise to maintain the normal operation of the mobile toilet.
Additionally, the specific classification of mobile toilets as fixed assets in an enterprise's ledger may vary depending on the enterprise's own business nature and management needs. For example, they may be classified as 'Machinery and Equipment', 'Structures', 'Special Equipment', or 'Mobile Service Facilities'.