Accounting for the Purchase of Mobile Toilets
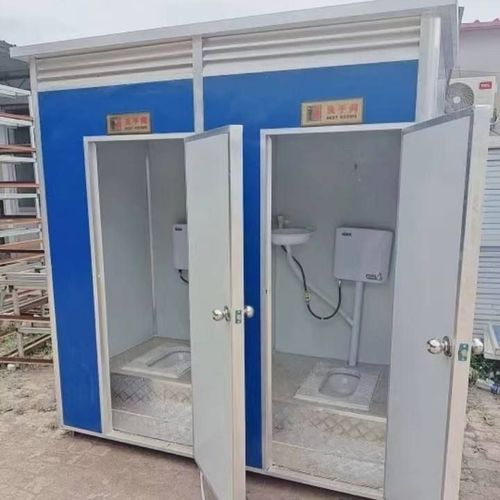
The accounting treatment for a company's purchase of mobile toilets should be recorded under the 'Fixed Assets' account and depreciated according to the category of tools and furniture. Here is a detailed analysis:
I. Criteria for Recognizing Fixed Assets
According to 'Accounting Standards for Business Enterprises No. 4 - Fixed Assets', fixed assets must meet two conditions simultaneously:
- Purpose of Holding: Held for production, operation, or management. Mobile toilets, as long-term sanitary facilities used by enterprises in their daily operations, meet this condition.
- Useful Life: Exceeding one accounting year. Although mobile toilets are movable, their designed lifespan typically exceeds one year, and enterprises do not dispose of them shortly after purchase, thus satisfying the requirement for long-term use. Conclusion: Mobile toilets meet the definition of fixed assets and should be accounted for as long-term assets.
II. Selection of Accounting Accounts
The following incorrect options should be excluded:
- Administrative Expenses (A): Used to account for short-term administrative expenses (such as office supplies and travel expenses). As a long-term asset investment, the value of mobile toilets needs to be allocated over multiple accounting periods. Directly recording them as administrative expenses would result in an overstatement of current expenses, violating the accrual basis principle.
- Intangible Assets (B): Intangible assets refer to non-monetary assets without physical form (such as patent rights and trademark rights). Mobile toilets have a clear physical form and obviously do not fall into this category.
- Long-term Deferred Expenses (C): Applicable to expenses with an amortization period exceeding one year (such as leasehold improvement expenditures). Mobile toilets are independent assets, and their value is released through depreciation rather than amortization, making this option inapplicable. Correct Option: They should be recorded under the 'Fixed Assets' account because they have a relatively high value and a useful life exceeding one year, meeting the requirements for fixed asset accounting.
III. Basis for Depreciation Classification
The depreciation category of mobile toilets should be determined based on their usage function. Compared to buildings or machinery and equipment, their function is closer to that of tools or furniture (such as mobility and auxiliary use), and their depreciation period is usually relatively short (e.g., 5-10 years), which is more in line with the actual usage situation of the tools and furniture category. Therefore, it is recommended to calculate depreciation according to the tools and furniture category.
IV. Differences in Handling by Administrative Institutions
If purchased by administrative institutions, it is necessary to distinguish between financial accounting and budget accounting:
- Financial Accounting Entries:
- Debit: Fixed Assets
- Credit: Fiscal Appropriation Revenue/Zero-Balance Account Usage Quota/Accounts Payable/Bank Deposits, etc.
- Budget Accounting Entries:
- Debit: Administrative Expenditures/Business Expenditures/Other Expenditures, etc.
- Credit: Fiscal Appropriation Budget Revenue/Fund Balance. Core Logic: Both administrative institutions and enterprises account for fixed assets as the core, but the sources of funds and expenditure accounts need to be adjusted according to the budget management system.