Back to blog
Article
Cost Accounting for Prefabricated House Finished Products
Admin September 18, 2026
Cost accounting for prefabricated house finished products requires a comprehensive analysis from four aspects: cost composition, accounting methods, cost advantages, and industry data.
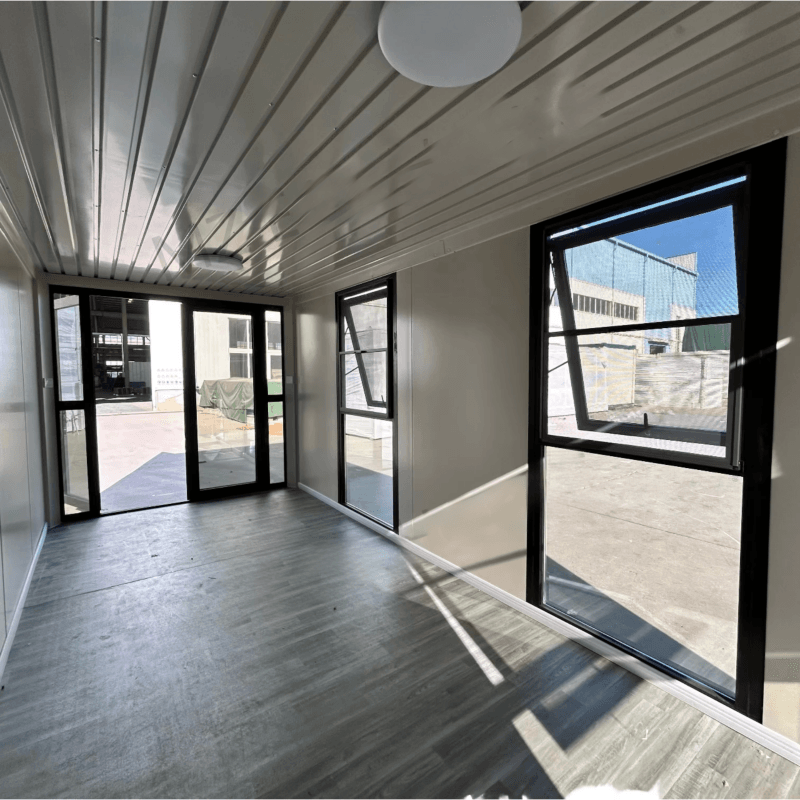
I. Cost Composition Elements
- Material Costs: Accounting for 60%-70% of the total cost, these primarily include cement, steel bars, sand, and gravel. Prefabricated houses typically use C30 or higher-grade concrete, paired with national standard steel bars. The proportion of raw material costs is high and significantly affected by fluctuations in the building materials market.
- Mold Costs: Making up 5%-8% of the total cost, molds are a one-time investment, amortized over each house. Their price is influenced by material, craftsmanship, and customization level, with high-precision steel molds costing more than ordinary ones.
- Transportation Fees: Due to the large volume and heavy weight of prefabricated houses, transportation costs are calculated based on mileage or cargo volume and weight. Cross-province transportation fees increase significantly, considering loading, unloading, and transportation losses.
- Installation Fees: Including equipment rental, labor costs, and on-site lifting, splicing, and fixing procedures, these typically account for 10%-15% of the total cost, influenced by construction efficiency and regional labor costs.
- Foundation Treatment Fees: These vary greatly depending on geological conditions. For example, soft soil foundations may require pouring concrete cushions or strip foundations, with costs potentially accounting for 5%-10% of the total.
- Energy Costs: Producing a single cubic meter of component consumes 80-120 kWh of electricity and 0.5-1 ton of steam, with energy costs accounting for 8%-12% of the total, influenced by energy prices and production efficiency.
II. Cost Accounting Methods
A comprehensive approach combining the "batch method + output ratio method + workload method" is used:
- Batch Method: Costs are collected by project batch, suitable for customized products.
- Output Ratio Method: Multiple raw material costs are allocated, such as concrete and steel bars being distributed based on usage ratios.
- Workload Method: Mold depreciation is calculated, with costs amortized based on usage frequency or output.
This method addresses three core issues: allocation of multiple raw materials, mold depreciation accounting, and customized cost collection.
III. Cost Advantages
- Low Material Waste: Standardized factory production reduces material waste by 20%-25%.
- Shortened Construction Period: Modular lifting operations improve construction efficiency by 40%-50% compared to traditional methods.
- Low Lifecycle Costs: Maintenance costs are 35%-45% lower than those of brick-and-mortar structures, demonstrating significant long-term economic benefits.
IV. Industry Data Reference
Taking 42 projects in East China from 2020 to 2023 as an example, the average weight of a 200㎡ single-story prefabricated house is 85 tons/m³, with a comprehensive cost of 62%-68% of traditional structures, verifying its cost advantages.
Related