Tax Code for Mobile Toilets
The tax code for mobile toilets should be determined based on their primary materials and structural characteristics. Common scenarios are as follows:

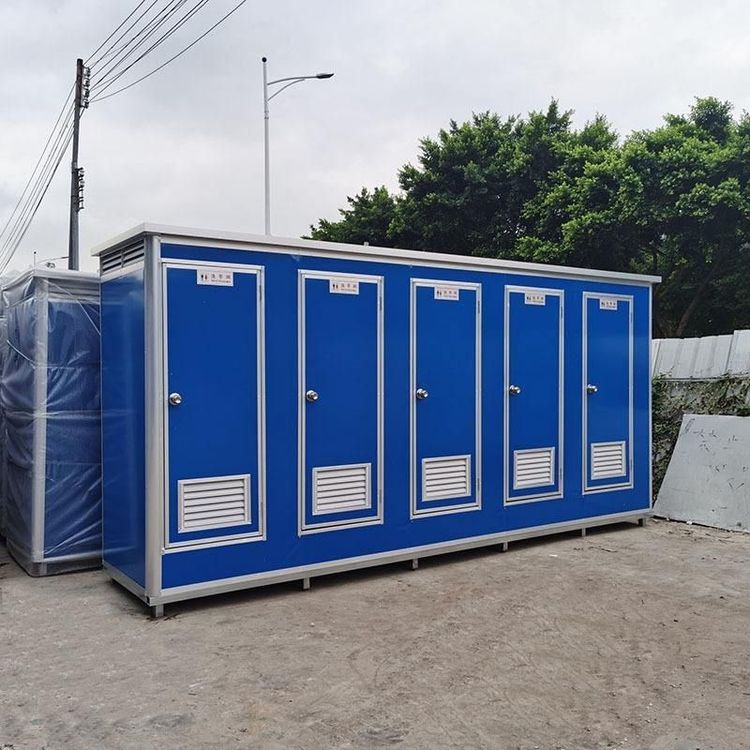
If the main materials and structural characteristics of the mobile toilet fall under the 'container' category, its tax classification code is 1080409, with the tax classification name being container and the invoicing product name being metal products*mobile toilet. This code is typically applicable to toilet facilities with a metal frame as the main structure and mobility features. The applicable tax rate for general taxpayers is 13%, and the levy rate for small-scale taxpayers is 3%.
If the main material of the mobile toilet is ceramic, its tax classification code may be the same as that for ceramic sanitary products, i.e., 108011001. This code is applicable to mobile toilets primarily made of ceramic materials (such as ceramic toilets and washbasins). The applicability of this code should be judged based on the proportion of ceramic components in the overall structure.
If the main material of the mobile toilet is metal (non-container type), its tax classification code may be similar to that for metal sanitary products, such as 109013101. The specific code should be further subdivided based on the type of metal (e.g., stainless steel, aluminum alloy) and its intended use. For example, different sub-codes may apply to metal brackets and metal casings.
If the mobile toilet includes plastic components (such as plastic water tanks and plastic partitions), the tax classification codes for these components should be declared according to the corresponding codes for plastic sanitary products. Common codes include 107060109 (plastic sanitary equipment fittings) or 107060111 (other plastic sanitary equipment). The appropriate code should be selected based on the function of the component.
Notes:
- The determination of the tax code should be based on the actual materials and structure of the mobile toilet. If there are multiple materials mixed, corresponding codes should be declared separately or classified according to the main material.
- There may be slight differences in the applicability of codes among tax departments in different regions. It is recommended to consult local policies or tax authorities for confirmation.
- When issuing invoices, ensure that the product name matches the tax classification code to avoid tax risks caused by incorrect coding.
Reference source: Tax Classification Code Table (Container Category)
Reference source: Tax Classification Code Table (Sanitary Products Category)