Profitability of Mobile Toilets
The profitability models of mobile toilets mainly include four directions: leasing, equipment sales, government-enterprise managed operation and maintenance, and technological dividends. Combined with policy support and market demand, the overall industry outlook is positive, but it needs to address challenges such as compliance and competition.
I. Leasing Model: Core Source of Profit, Diverse Scenarios, and Policy-Driven
The leasing model accounts for more than 60% of the market share, generating continuous cash flow through 'equipment rental + operation and maintenance services'. Its profit scenarios include:
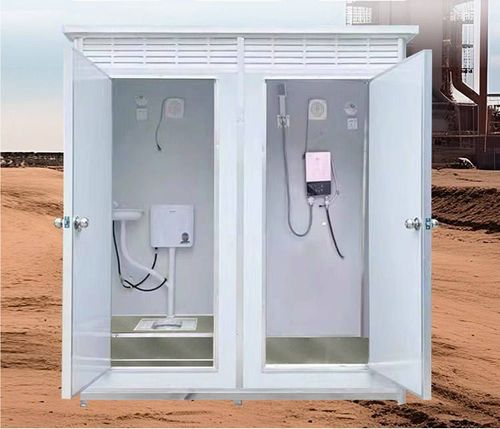
- Rigid Demand Scenarios: Construction sites are mandated by regulations to provide temporary toilets, with stable monthly rentals and payments. Cultural and tourism events (such as music festivals and marathons) see high premiums for short-term rentals during peak seasons, requiring advance preparation of toilet units. Municipal emergencies (such as flood prevention and disaster relief) often adopt a bundled 'leasing + operation and maintenance' model. Remote areas (such as mines and wilderness projects) have strong demand for ecological mobile toilets (microbial degradation, packing-type).
- Policy Support: Policies such as the 'Toilet Revolution' promote the popularization of modular public toilets. Failure to provide them at construction sites and events can result in penalties, leading环卫 (sanitation) projects to adopt a light-asset leasing model.
- Premiumization: Smart toilets equipped with solar power, waterless ecology, and IoT monitoring (for fecal waste levels and odors), as well as luxury mobile toilets (for weddings and events), command high unit prices and offer larger profit margins.
II. Equipment Sales: Fierce Competition, Low Gross Margin
Direct sales to municipalities, scenic spots, and engineering companies face severe market homogenization and price wars, resulting in low gross margins. Differentiating through operation and maintenance services or ecological/smart products is necessary.
III. Government-Enterprise Managed Operation and Maintenance: Long-Term Stable Orders
Winning bids for sanitation PPP and scenic spot public toilet托管 (managed operation) projects provides stable revenue through long-term operation and maintenance services.
IV. Technological Dividends: Differentiated Profitability of Vacuum Toilets
Vacuum toilets achieve technological premiums through water conservation, cost reduction, flexible deployment, and fecal waste resource utilization:
- Water Conservation and Cost Reduction: A single flush uses only 0.5-0.8L, saving over 80% of water compared to traditional toilets, with annual water savings exceeding 3,000 tons (based on daily usage by 1,000 people), directly reducing water costs. One scenic spot saw a 70% reduction in annual maintenance costs after switching.
- Flexible Deployment Premium: Thin and bendable pipes eliminate the need for ground excavation, shortening construction periods by 70%. In areas without pipelines, such as plateaus and deserts, rental premiums are significant.
- Fecal Waste Resource Utilization: After harmless treatment, fecal waste can be converted into organic fertilizer or biofuel. One leasing company increased its annual revenue by over 200,000 yuan through cooperation.
V. Industry Risks and Challenges
Attention should be paid to compliance costs (such as fecal waste removal qualifications), homogeneous competition, seasonal fluctuations (idle equipment during winter off-seasons), operational costs (equipment depreciation, manual cleaning, etc.), and payment cycle pressures (long payment cycles for municipal clients).
VI. Market Size and Trends
In 2024, the market size of China's ecological mobile toilet industry reached 1.87 billion yuan, a year-on-year increase of 14.3%, and is expected to continue growing in 2025. Water-saving (58% market share) and waterless (35% market share) ecological toilets dominate the market, with microbial degradation (46% adoption rate) and foam sealing (29% market share) technologies being the mainstream.