Input Tax on Mobile Toilets
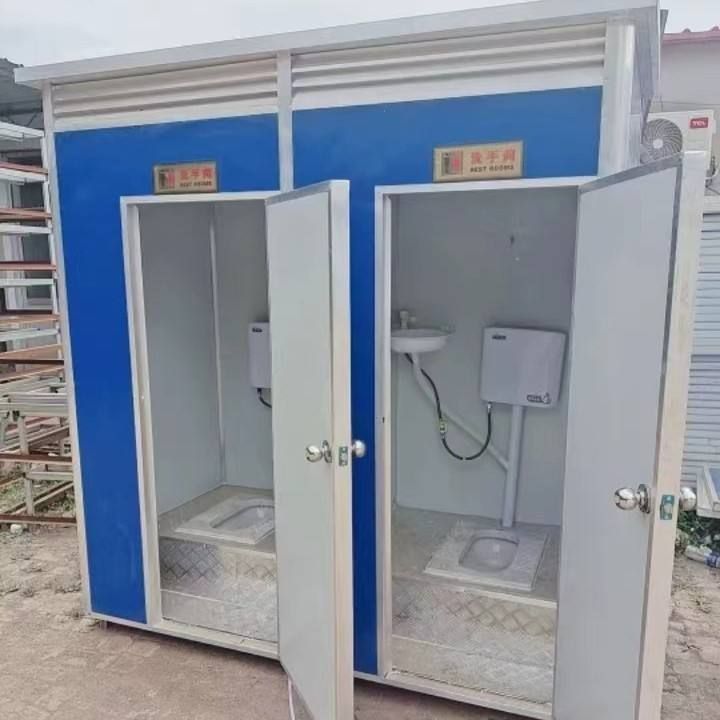
Input tax on mobile toilets can be deducted under certain conditions. The specific analysis is as follows:
Basis for Deduction
According to Article 8 of the Interim Regulations of the People's Republic of China on Value-Added Tax, input tax refers to the amount of value-added tax paid or borne by taxpayers when purchasing goods, labor, services, intangible assets, or real estate. As a purchased good, the input tax on mobile toilets can be deducted if the conditions are met. This provision provides a basic legal framework and theoretical basis for the deduction of input tax on mobile toilets.
Specific Deduction Conditions
- Obtaining a VAT Special Invoice: If a taxpayer purchases a mobile toilet from a seller and the seller issues a VAT special invoice with the VAT amount clearly stated on it, then this portion of the tax can be deducted as input tax. This is the most common method of deduction, ensuring the accuracy and legality of tax deductions through standardized invoice management.
- Obtaining a Customs Import VAT Special Payment Certificate: When a mobile toilet is imported through customs, the taxpayer needs to obtain a Customs Import VAT Special Payment Certificate. As long as the corresponding VAT amount is stated on the payment certificate, this tax amount can also be used for deduction. This method mainly applies to imported mobile toilets, ensuring the reasonable deduction of VAT in the import process.
Deduction Prerequisites and Restrictions
Although input tax on mobile toilets can be deducted under the above circumstances, there is an important prerequisite: it must be used for VAT-taxable projects. If the mobile toilet is used for non-VAT-taxable projects, such as projects subject to the simplified tax calculation method, VAT-exempt projects, collective welfare, or personal consumption, its input tax cannot be deducted from the output tax. This is to ensure the rationality and fairness of VAT deductions and prevent taxpayers from evading tax obligations through improper uses.
In conclusion, whether input tax on mobile toilets can be deducted requires a comprehensive consideration of multiple factors, including whether valid deduction certificates have been obtained and whether the usage complies with regulations. Taxpayers should operate in strict accordance with tax regulations when conducting relevant business to safeguard their legitimate rights and interests and avoid tax risks.