Mobile Toilet Industry Report
The core content of the mobile toilet industry report is as follows:

Market Size and Growth
In 2024, the market size of eco-friendly mobile toilets in China reached 1.87 billion yuan, representing a year-on-year increase of 14.3%. The demand on the eastern coast accounted for over 40%, with significant growth in the central and western regions. The global market is expected to reach 790 million US dollars by 2031, with a compound annual growth rate of 7.1%. The Chinese portable toilet market continues to expand rapidly, leveraging benefits such as an aging population, the booming outdoor economy, and emergency infrastructure construction, transitioning from medical aids to consumer products for the general public.
Product Classification and Technological Trends
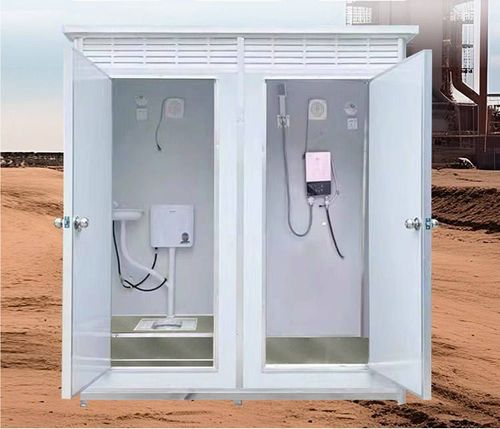
Chinese products are divided into two main directions: Domestically, mainstream categories include simple models (PE plastic one-piece molding, relying on disposable waste bags, weighing 1.5-3 kg, with high cost-effectiveness), packaged models, and self-contained fresh and wastewater models. Overseas high-end segments include vehicle-mounted pull-out models, elderly care barrier-free models, and biodegradable eco-friendly models. Technologically, microbial degradation technology (adoption rate of about 46% in new projects in 2024) and foam sealing technology (market share of about 29%) have become mainstream, with solar power and intelligent monitoring becoming standard features in high-end products. Among eco-friendly mobile toilets in China, water-saving models account for 58% of the market share, suitable for places with stable water supply such as urban parks and schools; waterless models account for 35%, used in remote areas and nature reserves without water supply and drainage systems.
Competitive Landscape
In 2024, the top five enterprises in the Chinese eco-friendly mobile toilet market accounted for nearly 60% of the market share, with small and medium-sized enterprises focusing on niche areas such as products suitable for high-altitude regions and extreme climate designs. In the global market, the top ten manufacturers accounted for 65% of the market share in 2024, with major producers including Satellite Industries, PolyJohn, Thetford, and Dometic.
Driving and Hindering Factors
Driving factors include increased urbanization and infrastructure construction, more large-scale public events, stricter environmental regulations, the development of the tourism and leisure industry, and growth in emergency demand. Hindering factors include high maintenance costs, limited user experience, inconvenience in transportation and storage, pressure on environmental treatment, and intense market competition.
Industry Pain Points and Suggestions
Pain points are concentrated on insufficient sealing and comfort, high operation and maintenance costs, and pressure in implementing environmental standards. Suggestions include providing strategies for technological upgrades and niche market focus for production enterprises, distributors, and industry associations to promote business and standardized development.