Mobile Toilet as Fixed Assets
Mobile toilets generally qualify as fixed assets, but certain conditions must be met. Here is a detailed analysis:

Compliance with the Legal Definition of Fixed Assets
According to Article 57 of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China, fixed assets refer to non-monetary assets held and used by enterprises for more than 12 months for the production of products, provision of labor services, leasing, or business management. These include buildings, structures, machinery, equipment, transportation vehicles, and other equipment and appliances related to production and business activities. If a mobile toilet is held and used by an enterprise for business management purposes (such as in tourist attractions, construction sites, or temporary event venues) and is expected to be used for more than 12 months, it meets the basic description of fixed assets in this definition.
Meeting the Recognition Criteria of Accounting Standards
According to Articles 3 and 4 of the Accounting Standards for Business Enterprises No. 4 - Fixed Assets (2006 Edition), fixed assets must meet two conditions simultaneously:
- Purpose of Holding: Held for the production of goods, provision of labor services, leasing, or business management;
- Economic Benefits and Measurement: Have a useful life exceeding one accounting year, with economic benefits related to the asset likely to flow into the enterprise and costs reliably measurable. If a mobile toilet is used by an enterprise for an extended period (such as as a supporting facility in tourist attractions or temporary toilets at construction sites), its useful life typically exceeds one accounting year, and it can bring continuous economic benefits to the enterprise (such as improving service quality and meeting operational needs). Additionally, the purchase cost can be clearly measured, so it can be recognized as a fixed asset.
Accounting Treatment and Classification
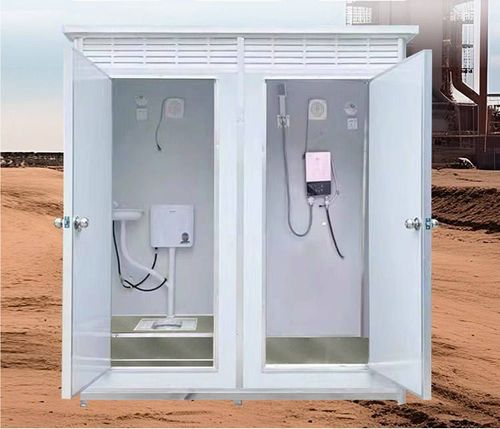
In accounting practice, although mobile toilets are movable, they are usually classified as fixed assets and depreciated under the category of tools and furniture due to their relatively long useful life and service for business management. Their accounting classification varies depending on industry and enterprise characteristics and may be recorded under accounts such as 'machinery and equipment', 'structures', 'special equipment', 'mobile service facilities', 'public infrastructure', 'sanitation equipment', 'green assets', 'tourist supporting facilities', 'temporary facilities', or 'transportation vehicles'. For example, tourist attractions may classify them as 'tourist supporting facilities', while sanitation enterprises may classify them as 'sanitation equipment'.
Special Circumstances
If a mobile toilet is temporarily leased or used for less than 12 months, it does not meet the definition of fixed assets and should be treated as low-value consumables or expenses. Additionally, if a mobile toilet is a public facility invested in and constructed by the government (such as municipal mobile public toilets), its property rights and accounting treatment need to be determined according to specific contracts or policies and may not be included in the scope of enterprise fixed assets.