Mobile Toilet Counted as Fixed Asset
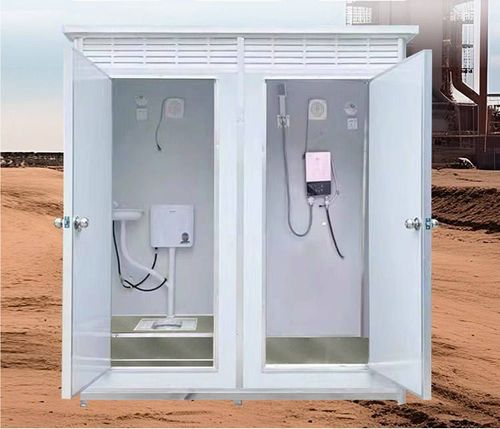
Mobile toilets can be counted as fixed assets. Here is a detailed analysis:

Compliance with the Tax Law Definition of Fixed Assets
According to Article 57 of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China, fixed assets refer to non-monetary assets held by enterprises for the production of products, provision of labor services, leasing, or business management, with a usage period exceeding 12 months. These include houses, buildings, machinery, mechanical equipment, transportation tools, and other equipment, appliances, and tools related to production and business activities. As a facility held by enterprises for business management purposes, mobile public toilets, if their usage period may exceed 12 months, meet the basic description of fixed assets in this definition. For example, when enterprises purchase mobile public toilets for use in scenic spots, construction sites, and other locations to provide toilet services for tourists or employees, their holding purpose is for business management, and their usage period is usually long, meeting the tax law's requirements for the usage period of fixed assets.
Meeting the Recognition Criteria of Accounting Standards
According to Articles 3 and 4 of the Accounting Standards for Business Enterprises No. 4 - Fixed Assets (2006 Edition), fixed assets must meet two conditions simultaneously: first, they are held for the production of goods, provision of labor services, leasing, or business management; second, their service life exceeds one accounting year, and the economic benefits related to the fixed assets are likely to flow into the enterprise, and the cost of the fixed assets can be reliably measured. Mobile public toilets are usually used by enterprises or governments to provide public services, and their holding purpose meets the first condition. Moreover, as tangible assets, their service life usually exceeds one accounting year. After purchasing them, enterprises can obtain corresponding economic benefits by providing public services, and the cost can also be reliably measured, meeting the second condition. Therefore, they can be recognized as fixed assets.
Accounting Treatment Methods
In accounting treatment, although mobile toilets are movable, since their service life usually exceeds one accounting year and they are used for business management by enterprises, they should be counted as fixed assets and generally depreciated according to the category of tools and furniture. However, there may be differences in specific classification among different industries and enterprises. For example, they may be labeled as 'mechanical equipment', 'structures', 'special equipment', 'mobile service facilities', 'public infrastructure', 'sanitation equipment', 'green assets', 'tourism supporting facilities', or 'temporary facilities'.