Mobile Toilet as Fixed Asset
The purchased mobile toilet can be classified as a fixed asset. Detailed analysis is as follows:

I. Compliance with the Definition of Fixed Assets
According to Article 57 of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China, fixed assets refer to non-monetary assets held by enterprises for the production of products, provision of labor services, leasing, or business management, with a usage period exceeding 12 months. These include houses, buildings, machinery, equipment, transportation tools, and other equipment, appliances, and tools related to business operations. As a facility held by enterprises for business management purposes with a potential usage period exceeding 12 months, mobile toilets are directly related to business operations and meet the basic definition of fixed assets.
II. Meeting the Recognition Criteria for Fixed Assets
Based on Articles 3 and 4 of the Accounting Standards for Business Enterprises No. 4 - Fixed Assets (2006 Edition), fixed assets must meet two conditions simultaneously: first, they are held for the production of goods, provision of labor services, leasing, or business management; second, their useful life exceeds one accounting year, and it is probable that economic benefits related to the asset will flow into the enterprise, with costs that can be reliably measured. If the useful life of a mobile toilet exceeds one year, and the enterprise can reasonably expect to generate economic benefits through its use or leasing, while the procurement cost can be clearly accounted for, then it meets the recognition criteria.
III. Classification in Accounting Treatment
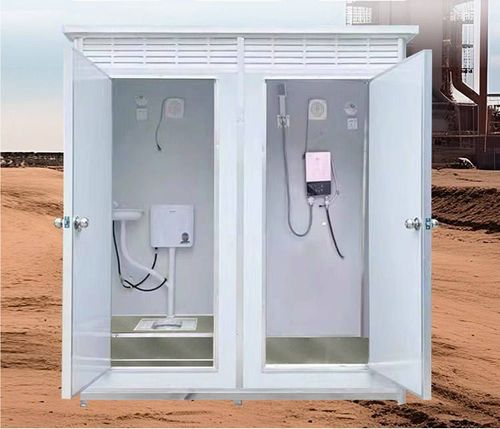
Although mobile toilets are movable, their useful life typically exceeds one accounting year and they serve business management purposes. Therefore, they should be classified as fixed assets. In practice, if their unit value is relatively high (e.g., over 10,000 yuan), they are generally depreciated under the category of 'houses and buildings'. For example, if a mobile toilet purchased by an enterprise meets the above conditions, it needs to be depreciated over its estimated useful life (e.g., 5 years) and regularly assessed for residual value.
IV. Determination of Tax Basis
According to Article 58 of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China, the tax basis of purchased fixed assets includes the purchase price, related taxes, and other expenses directly attributable to bringing the asset to its intended use (e.g., transportation costs, installation costs). When purchasing a mobile toilet, an enterprise must include all expenses such as invoice amount, transportation costs, and commissioning costs in the tax basis, serving as the tax basis for subsequent depreciation or disposal.