Where to Record Mobile Toilet Accounting Entries
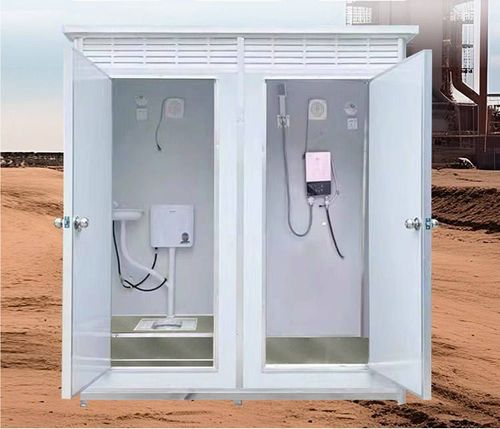
Mobile toilet accounting entries are typically recorded under fixed asset accounts, but this depends on the specific circumstances:

1. General Case: Record under Fixed Asset Accounts If the mobile toilet is used for more than 12 months, it meets the definition of a fixed asset under tax law (non-monetary assets held by an enterprise for the production of products, provision of labor services, leasing, or business management, with a usage period exceeding 12 months). It also satisfies the recognition criteria for fixed assets under accounting standards (held for the purpose of producing goods, with a useful life exceeding one accounting year, with probable inflow of economic benefits to the enterprise, and with a reliably measurable cost). In this case, it should be recorded under fixed asset accounts. Generally, depreciation is calculated under the category of tools and furniture, with the depreciation period and residual value rate determined according to the enterprise's accounting policies.
2. Low-Value Case: Directly Record under Administrative Expenses If the mobile toilet has a relatively low value (e.g., around 2,000 yuan), it can be directly recorded under administrative expenses - other expenses according to the principle of materiality, without being capitalized as a fixed asset. This approach simplifies the accounting process, but it is necessary to ensure that the amount complies with the enterprise's established standards for low-value consumables.
3. Special Purpose Case: Record under Welfare Expenses If the company purchases a mobile toilet specifically for use by employees in the workshop, it is considered a welfare facility provided to employees and can be recorded under welfare expense accounts. Note that welfare expenses must be deductible before tax within 14% of the total wage bill, and any excess must be adjusted for tax purposes.
4. Industry-Specific Classification Differences The accounting classification of mobile toilets varies according to industry characteristics:
- Industrial/Construction Industry: They may be classified as 'machinery and equipment', 'temporary facilities', or 'special equipment'. For example, a construction company may consider them temporary facilities during construction.
- Service/Municipal Industry: Service-oriented enterprises may view them as 'mobile service facilities', while municipal departments may classify them as 'public infrastructure' or 'sanitation equipment'.
- Environmental Protection/Energy Industry: Environmentally friendly mobile public toilets may fall under the 'green assets' category, while those with photovoltaic power generation functions must be split into 'fixed assets' and 'new energy equipment'.
- Special Function Toilets: Toilets with intelligent systems must be accounted for separately (e.g., hardware recorded under fixed assets, software under intangible assets); luxury toilets with maternity rooms may have a sub-category under 'fixed assets - sanitation facilities - special functions'.
- Other Scenarios: Refitted truck-style toilets may be classified as 'transport vehicles' or 'special equipment'; shared toilet operators may need to switch between 'fixed assets' and 'inventory'; and military field toilets are directly classified as 'war preparation supplies'.
Enterprises should select the most appropriate accounts for核算 (this word should be translated as 'accounting' in the context, but kept as is here to show original text placement, replace with proper accounting term in final version if needed) based on actual usage, industry norms, and tax law requirements, ensuring consistency between accounting treatment and tax reporting.