Back to blog
Article
Export Tax Refund for Container Houses
Admin September 15, 2026
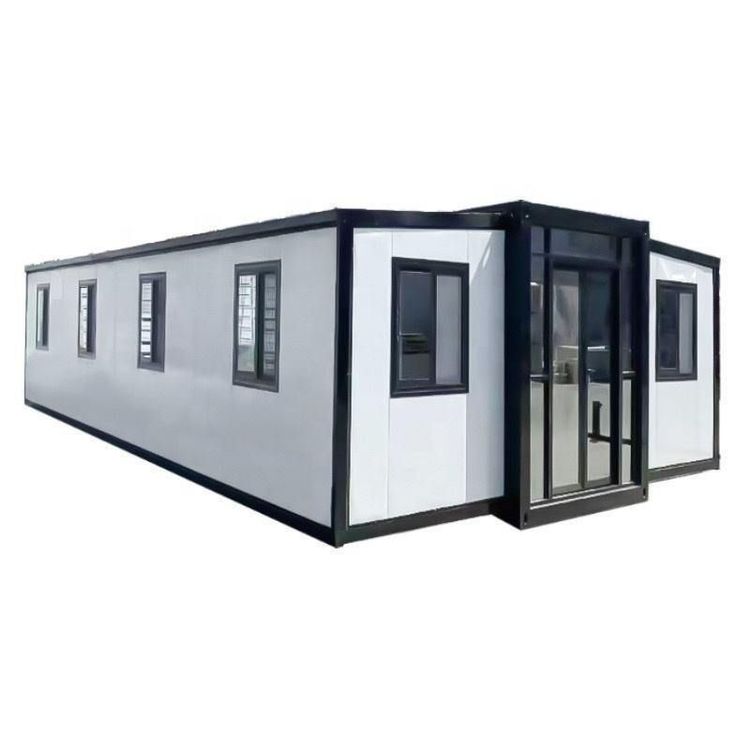
The export tax refund rate for container houses (taking mobile homestay space capsules as an example) is 13%. The 'exemption, credit, and refund' management method applies, and compliance requirements and accurate classification must be met.

Tax Refund Rate and Scope of Application
According to China Customs' latest HS code rules in 2026, the value-added tax export tax refund rate for mobile homestay space capsules (classified as 'other movable houses' with the tax number 9406900090) is 13%. This rate applies to production enterprises and foreign trade enterprises that are general VAT taxpayers, and the following conditions must be met:
- Product Attributes: With steel structures or aluminum alloys as the main frames, integrating water and electricity, sanitation, ventilation, and other systems, they have complete accommodation functions and can be moved as a whole.
- Compliance Requirements: Export enterprises need to handle tax refunds through the electronic tax bureau or the international trade 'single window'. Initial filing can be done with a 'one-form application', but customs authorities have strengthened the verification of document filing and the authenticity of foreign exchange receipts, requiring the 'four-flow consistency' (contract flow, goods flow, capital flow, and invoice flow).
Operation Procedures and Precautions
HS Code Classification:
- Mobile homestay space capsules need to be classified under 9406900090. Incorrect classification may lead to tax refund failures or trigger customs inspections.
- Avoid misclassification as 'steel structural parts' (7308 series, with a tax refund rate of 9%) or 'containers' (8609 series, with a tax refund rate of 10%). The latter requires meeting ISO size certification requirements, and non-compliant classification may face the risk of tax repayment and late fees.
Tax Refund Management Methods:
- Production enterprises implement the 'exemption, credit, and refund' method: Exempt from value-added tax on export links, input tax amounts are first offset against the VAT payable on domestic sales, and the un-offset part is refunded.
- After policy optimization, the entire process can be handled 'non-contact'. However, strict compliance with document filing and the authenticity of foreign exchange receipts is required.
Policy Background and Adjustments
- In September 2025, the Ministry of Commerce included 'prefabricated travel pods' in the list of encouraged exports, raising the tax refund rate from 9% to 13%, consistent with the tax rate in the State Administration of Taxation's database in 2026, reflecting policy continuity.
- The 'Opinions on Promoting the Stable Growth of Foreign Trade' approved by the State Council clearly states measures such as accelerating export tax refunds and expanding financing scales to reduce corporate capital pressures.
Risk Prevention and Control
- Enterprises need to ensure the authenticity of trade and avoid fabricating trade relationships or falsely declaring exports; otherwise, they may constitute the crime of defrauding export tax refunds and face criminal penalties.
- Tax authorities verify documents and foreign exchange receipts through big data, and enterprises need to retain complete transaction records for inspection.