How to Depreciate Mobile Toilets for Companies
The depreciation of mobile toilets for companies needs to be determined based on their specific classification and usage. The depreciation periods and handling methods under common classifications are as follows:

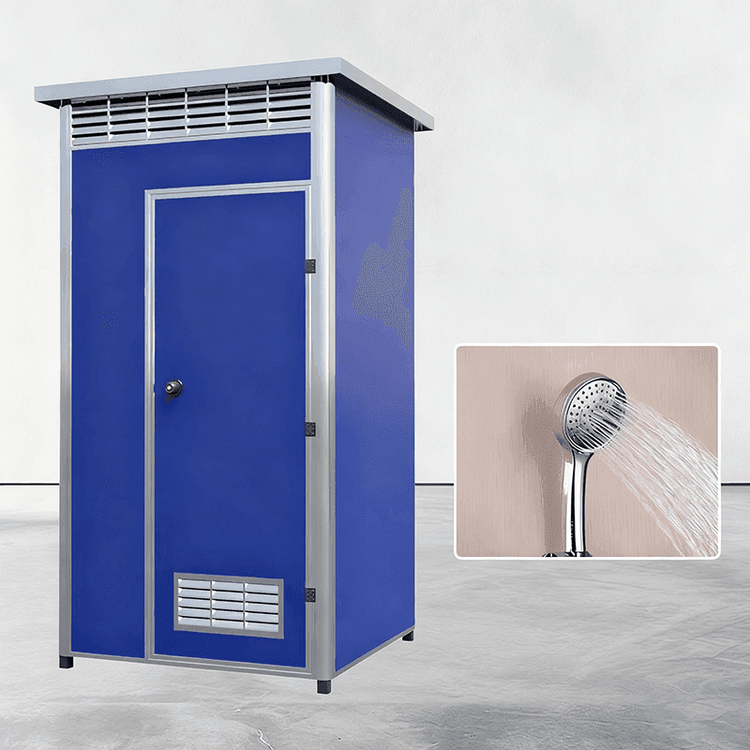
I. Classified as Instruments, Tools, Furniture, etc., Related to Production and Business Activities If mobile toilets are classified as instruments, tools, or furniture directly related to production and business activities (such as temporary facilities used at construction sites, scenic spots, etc.), they are generally depreciated according to the category of tools and furniture. According to tax laws and accounting practices, the depreciation period for such assets is generally not less than 3 years, and the specific period needs to be comprehensively determined based on factors such as the company's expected consumption mode and actual usage intensity. For example, if the toilet materials are highly durable and well-maintained, the company may appropriately extend the depreciation period; if the usage frequency is high and the wear and tear are rapid, the period may be shortened, but it must comply with the minimum period requirements set by tax laws.
II. Classified as Houses or Buildings If mobile toilets are identified as houses or buildings (such as fixed-installed container-type toilets with structural functions close to permanent buildings), their depreciation period must comply with the provisions of the Implementation Regulations of the Enterprise Income Tax Law of the People's Republic of China, which is generally 20 years. However, it should be noted that if the toilet design emphasizes mobility and convenience (such as being able to be hoisted and disassembled as a whole), and its structural functions are closer to those of movable equipment (such as movable panel houses), the depreciation period must be determined by referring to other relevant asset categories (such as mechanical equipment) rather than directly applying the 20-year standard for houses and buildings.
III. Accelerated Depreciation under Special Circumstances For mobile toilets whose actual service life is significantly shortened due to technological progress (such as material updates and design optimizations leading to the rapid obsolescence of old toilets) or harsh usage environments (such as high-corrosion and high-wear scenarios), companies may apply for accelerated depreciation. Specific methods include shortening the depreciation period or adopting accelerated depreciation methods such as the double-declining balance method and the sum-of-the-years'-digits method. However, the minimum depreciation period must not be less than 60% of the prescribed period (e.g., a minimum of 1.8 years for tools and furniture, and a minimum of 12 years for houses and buildings).
IV. Key Factors in Determining the Depreciation Period In addition to asset classification, companies also need to comprehensively consider the following factors:
- Material Quality: Durable materials such as stainless steel and anti-corrosion wood can extend the service life;
- Usage Frequency: A high average daily usage count will accelerate wear and tear;
- Maintenance and Upkeep: Regular cleaning and repairs can extend the actual service life;
- Environmental Conditions: Humid, high-temperature, or high-salt-fog environments will shorten the toilet's lifespan.
Companies should reasonably determine the depreciation period based on actual conditions and tax law requirements, and retain proof materials such as asset purchase contracts and usage records for tax inspection purposes.